Sell First or Buy First in Bakersfield? How to Decide
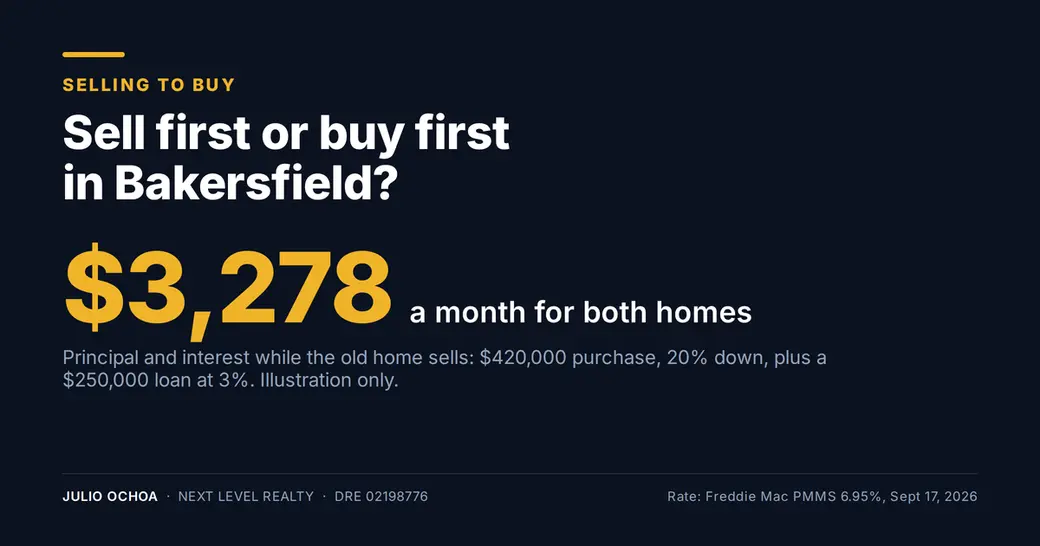
If you need the money from your current home to buy the next one, sell first or offer with a sale contingency. If you qualify for both payments and have the down payment without the sale, you can buy first. In the Bakersfield example below, that costs about $3,278 a month in principal and interest until the old house sells.
That is the short answer. The right choice depends on three things: how much equity you have, whether a lender will count both payments against you, and how fast homes like yours are selling right now. Here is how each one works in Bakersfield as of September 2026.
Why this question is harder in 2026
Two numbers set the stage. Freddie Mac's weekly survey put the average 30-year fixed rate at 6.95 percent on September 17, 2026, up from 6.76 percent the week before and 6.26 percent a year earlier. That is a national average, not a quote, but it tells you the new loan on your next home will likely cost more than the loan you have now.
At the same time, Bakersfield homes are not flying off the market. Redfin's data for the three months ending August 2026 shows a median sale price of $419,807, a median of 35 days on market, homes selling at 99.3 percent of list price, and 30.1 percent of listings taking a price cut. Across Kern County, a local lender's September 2026 market report counted 2,157 active listings as of September 1, 2026.
Put together: your house will probably sell, but not overnight, and not always at the first price. That gap is exactly where people buying and selling at the same time get squeezed.
What does it cost to carry two homes at once?
Here is a worked example. The purchase price is close to the Bakersfield median. The current loan is an illustration of an owner who bought or refinanced when rates were low. Your numbers will be different, so treat this as a way to see the math, not an estimate of your cost.
| Item | Assumption | Monthly principal and interest |
|---|---|---|
| Next home | $420,000 price, 20 percent down, $336,000 loan, 30 years at 6.95 percent (Freddie Mac average, September 17, 2026) | $2,224 |
| Current home | $250,000 loan balance, 30 years at 3.00 percent (illustration) | $1,054 |
| Both at once | Until the current home closes | $3,278 |
| Two months of overlap | Extra cost of the old payment only | $2,108 |
Property taxes, insurance, utilities and upkeep on the empty house come on top of that. If you want the rate side of this explained in more detail, I walked through it in what the latest rate move does to a Bakersfield payment.
The payment is only half of it. The other half is the down payment. In this example, 20 percent down on $420,000 is $84,000. If that money is sitting in your current home as equity, you cannot use it until the sale closes, unless you borrow against it first.
Will a lender count both payments?
Usually, yes. Under Fannie Mae's guidelines, a lender can leave your current home's payment out of your debt-to-income ratio only when two things are in hand: a signed sales contract on your current home, and confirmation that your buyer's financing contingencies are cleared. Until then, both payments count. You can read the rule yourself in Fannie Mae's Selling Guide, section B3-6-06.
That is why the first step is not a listing appointment or a tour. It is a lender conversation. Ask them one plain question: can I qualify with both payments, and if not, what do I need to show you before you drop the old one? My post on pre-approval versus pre-qualification explains why a full pre-approval matters even more when you are moving up.
Your four options, side by side
| Option | What it costs you | The risk | Works best when |
|---|---|---|---|
| Sell first, then buy | Possibly a short rental or a second move | You could be between homes for a while | You need your equity for the down payment |
| Sell first with a rent-back | Rent to your buyer for the extra days, if they agree | Your buyer may say no or ask a higher price for it | You want one move and a little breathing room |
| Buy with a sale contingency | A weaker offer in the seller's eyes | The seller can keep taking backup offers and push you to remove the contingency | Your home is priced right and likely to sell fast |
| Buy first, then sell | Two payments until the old home closes | If the sale drags, you carry both longer | You qualify for both and have the down payment in cash or a credit line |
Selling first
This is the lowest risk path. You know exactly what you walked away with before you commit to the next house. The cost is logistics. You may need a short lease or a storage unit, or you can ask your buyer for a rent-back, where you stay in the house for a set number of days after closing and pay them rent. Get the terms in writing as part of the sale contract.
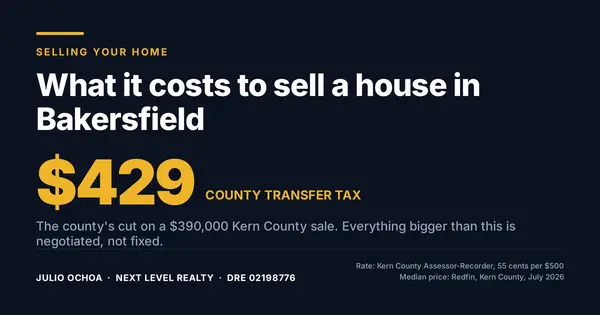
Before you list, know your real net. Commissions, escrow, title and prorated taxes come out of your price. I broke those down in what it costs to sell a house in Bakersfield.
Buying with a sale contingency
A sale contingency means your purchase depends on your current home selling. In California this is usually written on a California Association of Realtors form called COP. As the Tahoe Sierra Board of Realtors explains it, the default gives the buyer 17 days to get their current home under contract, unless both sides write in a different number. The seller can usually keep marketing the house, and if they accept a backup offer, they can require you to remove the contingency or cancel.
Sellers accept these more often when homes are sitting longer and price cuts are common. With 30.1 percent of Bakersfield listings taking a cut in the three months ending August 2026, some sellers will listen. A seller with multiple offers will not.
Buying first
This is the easiest move to live through and the hardest on your budget. You need to qualify with both payments, and you need the down payment from savings or from a home equity line opened on your current house. Many lenders will not open a new equity line on a home that is already listed for sale, so that conversation has to happen before the sign goes up.
How I would sequence it in Bakersfield right now
- Talk to a lender first. Find out whether you qualify with both payments and what your down payment has to come from.
- Get a realistic sale price for your home based on what similar homes nearby actually sold for, not what they were listed at.
- Subtract your selling costs and loan payoff to get your real net.
- Pick the option from the table above that fits your net and your approval.
- If you are listing first, prep and price it to sell inside the 35 day median, not to test the market.
- Line up the next home search at the same time, so you are ready to write an offer the week your home goes under contract.
If you are also moving across town, it helps to know the areas before you start. My northwest versus southwest Bakersfield comparison covers the practical differences.
Common questions
Can I buy a house in Bakersfield before selling mine?
Yes, if a lender approves you with both payments counted and you have the down payment without the sale. If either one is missing, you will need to sell first or write a sale contingency. A lender can tell you which in one conversation.
Do sellers accept contingent offers in Bakersfield?
Some do, especially on homes that have been listed a while or have already cut the price. A contingent offer is stronger when your home is already listed, priced right, and ideally already under contract.
How long does it take to sell a house in Bakersfield?
Redfin reports a median of 35 days on market for Bakersfield over the three months ending August 2026. Escrow usually adds about a month after that. Plan for the longer end, not the median.
What is a rent-back?
A rent-back is an agreement to stay in your home for a short period after it closes, paying the new owner rent. It is negotiated as part of the sale and gives you time to close on your next home without moving twice.
Will my lender count my old mortgage payment?
Usually, until you have a signed contract on the old home and your buyer's financing contingencies are cleared. That is the Fannie Mae rule, and many lenders follow it or something close to it. Ask your lender how they handle it before you make an offer.
The next step
Moving up is two transactions that have to fit together. I will tell you honestly which order makes sense for your numbers, even if the answer is to wait. If you are thinking about selling, start with my free seller guide at yourbakersfieldsellerguide.netlify.app, then call or text me and we will map it out.
Julio Ochoa | Next Level Realty | CalDRE 02198776 | 661-933-8428
Sources: Freddie Mac Primary Mortgage Market Survey, September 17, 2026. Redfin Bakersfield housing market data, three months ending August 2026. Kern County active listings from the Dan Ardis Bakersfield market report, as of September 1, 2026. Fannie Mae Selling Guide B3-6-06. Tahoe Sierra Board of Realtors guide to C.A.R. form COP.
Rate figures are national survey averages published by Freddie Mac on the dates shown and are not an offer of credit or a rate quote. Payment figures are principal and interest only and are illustrations, not estimates of your cost. Taxes, insurance, mortgage insurance and HOA dues are additional. Only a licensed lender can provide a rate and APR. Equal Housing Opportunity.
Categories
Recent Posts