Kern County Home Insurance: What the FAIR Plan Hike Costs You
The California FAIR Plan's 29.1 percent average rate increase takes effect October 15, 2026. In Kern County, 8,856 owner occupied single family homes were on the FAIR Plan as of June 30, 2026, paying an average of about $1,398 a year. After the increase that average lands near $1,805. Most of that exposure sits in the mountains, not in Bakersfield.
The numbers move a lot depending on which Kern County ZIP code you are buying in. And an insurance quote can change what a lender will approve you for.
What the FAIR Plan is, and why it matters even if you have never heard of it
The California FAIR Plan is the state's insurer of last resort. Not a government program, not funded by taxpayers. It is an association of licensed insurers that has to write a basic fire policy for owners who cannot get coverage on the open market. The FAIR Plan calls itself temporary, meant to hold a property until a regular carrier will take it back.
You care about it as a buyer for one reason. Your lender requires hazard insurance before it funds your loan. If no standard carrier will write the house you are buying, the FAIR Plan is what is left, and that premium goes straight into your monthly payment through the escrow account.
How many Kern County homes are on the FAIR Plan
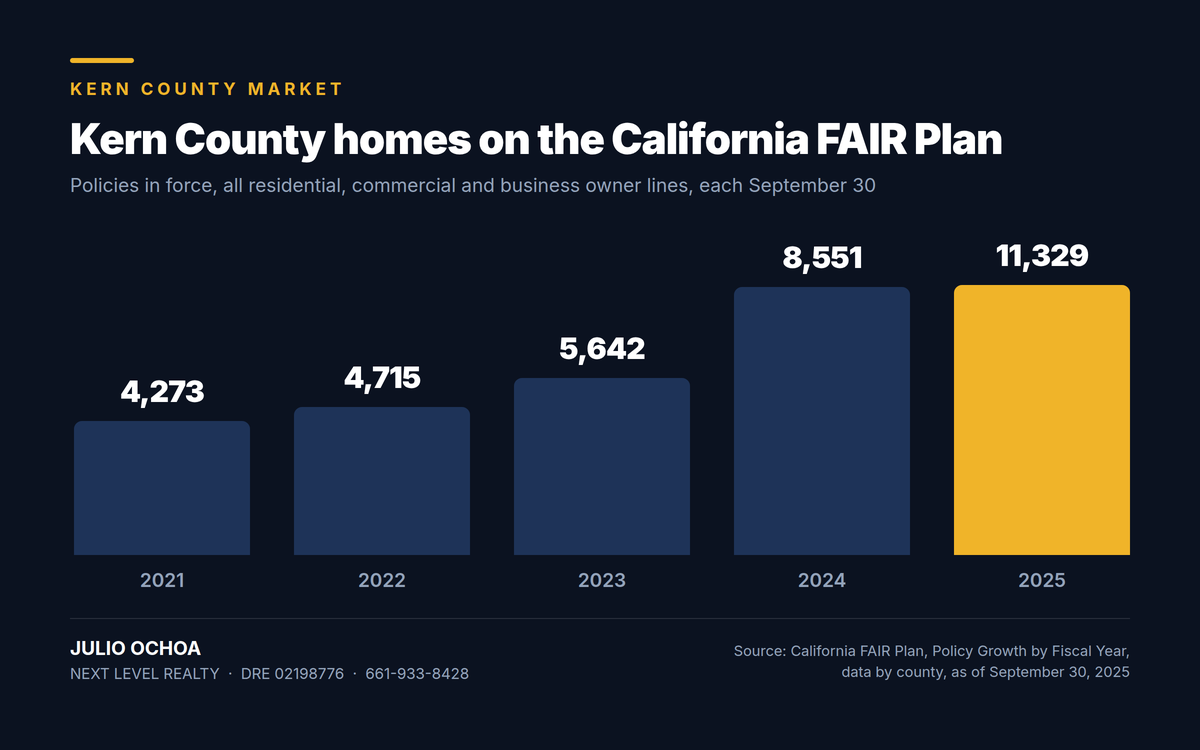
The FAIR Plan publishes its own numbers, which is where every figure below comes from. Across all residential, commercial and business owner policies, Kern County had 11,329 policies in force as of September 30, 2025. That is up 32 percent in one year and up 165 percent from 4,273 in 2021.
Narrowing to owner occupied single family homes, the category most buyers are in, Kern County had 8,856 FAIR Plan policies as of June 30, 2026.
Where in Kern County the FAIR Plan problem actually is
The concentration is in the mountain and foothill communities. The state has formally designated sixteen Kern County ZIP codes as distressed areas, meaning coverage is hard to find there. The Department of Insurance lists 662 distressed ZIP codes statewide.
| Community | ZIP | Owner occupied FAIR Plan policies | State designated distressed area |
|---|---|---|---|
| Tehachapi | 93561 | 1,892 | Yes |
| Frazier Park and Pine Mountain Club | 93222 | 863 | Yes |
| Frazier Park | 93225 | 745 | Yes |
| Wofford Heights | 93285 | 682 | Yes |
| Lake Isabella | 93240 | 650 | Yes |
| Bodfish | 93205 | 333 | Yes |
| Kernville | 93238 | 267 | Yes |
| Weldon | 93283 | 206 | Yes |
| Caliente | 93518 | 193 | Yes |
| Lebec | 93243 | 153 | Yes |
| City of Bakersfield, all eleven ZIP codes combined | 93301 through 93314 | 1,595 | No |
Read the last row again. Tehachapi alone carries more FAIR Plan policies than the entire city of Bakersfield.
Bakersfield is a different story, and one number surprised me
Of the 1,595 owner occupied FAIR Plan policies in the eleven Bakersfield city ZIP codes, 1,425 are in the FAIR Plan's own low wildfire risk band. None of those eleven ZIP codes is on the state's distressed list. So people in flat Bakersfield are landing on the insurer of last resort for reasons that mostly are not wildfire.
And the count is climbing fast. Bakersfield city ZIP codes held 1,702 FAIR Plan dwelling policies on September 30, 2024 and 2,654 a year later. That is 56 percent growth in twelve months, in ZIP codes the state does not consider distressed.
Be careful with that number. The published data shows the count, not the cause. The usual reasons a standard carrier walks away from a flat Bakersfield house are roof age, a prior claim, a vacant stretch, an older electrical panel, or a carrier pulling back from California. Your broker can tell you which one applies to a specific address. I cannot, and neither can a chart.
What 29.1 percent actually does to your monthly payment
Insurance is paid yearly and felt monthly. Here is what different annual premiums cost per month, and what that same monthly dollar amount would have supported in loan size at the 6.95 percent thirty year fixed average Freddie Mac published on September 17, 2026.
| Annual premium | Per month | Loan that same monthly amount would support |
|---|---|---|
| $1,017, Bakersfield FAIR Plan average, June 30, 2026 | $85 | $12,803 |
| $1,312, Bakersfield average after the 29.1 percent increase | $109 | $16,517 |
| $1,398, Kern County FAIR Plan average, June 30, 2026 | $116 | $17,600 |
| $1,805, Kern County average after the increase | $150 | $22,723 |
| $2,111, Kern mountain ZIP average after the increase | $176 | $26,576 |
| $3,600, a Frazier Park renewal reported in August 2024 | $300 | $45,321 |
| $7,000, the high end mountain residents reported in August 2024 | $583 | $88,124 |
The rule of thumb underneath that table is the useful part. At 6.95 percent over thirty years, every $100 a month of insurance premium is worth about $15,107 of loan amount. A buyer who moves from a Bakersfield average premium to a Frazier Park scale premium gives up roughly $32,500 of buying power on the same income. Nothing about the house changed. Only the insurance line did.
That is also why the insurance quote belongs early in your escrow, not the week before closing. If you want the rest of the payment math, I broke down what rate moves cost a Bakersfield buyer every month in a separate post, and what you will actually pay in Kern County property taxes covers the other big escrow line.
A FAIR Plan policy is not a homeowners policy
This trips up more buyers than anything else on this page. The basic FAIR Plan dwelling policy is fire coverage, not the all in one homeowners policy most people picture. The FAIR Plan itself tells policyholders to buy a separate Difference in Conditions policy, usually shortened to DIC, to cover most of the perils it does not.
- The FAIR Plan dwelling policy centers on fire and related perils.
- A Difference in Conditions policy from a regular carrier fills in the rest, and it is bought separately.
- Flood and earthquake are separate again, from separate policies.
- Two policies mean two premiums, so compare the combined cost, not the FAIR Plan number alone.
When somebody quotes you a FAIR Plan premium, ask what the DIC policy costs on top of it. That combined figure is what your lender will escrow, and it is what you compare against a standard policy.
What to do if you are buying in Kern County right now
- Get an insurance quote on the specific address during your inspection contingency, not after. The address, the roof age and the year built drive the quote, so it cannot be estimated from a neighborhood.
- Ask the seller who currently insures the house and what they pay. A house that a standard carrier is happy with today is worth a lot.
- Send the quote to your lender before you remove contingencies, alongside the rest of your Bakersfield closing costs. The premium changes your debt to income ratio, and it is better to find that out while you still have an exit.
- If the quote comes back FAIR Plan only, price the Difference in Conditions policy in the same week and add the two together.
- Check the roof age. It is the single most common reason a carrier declines a flat Bakersfield house, and a seller sometimes has more room on that than on price.
What to do if you already own and just got a nonrenewal
A nonrenewal notice does not make the FAIR Plan your only option. Shop the open market with a licensed broker first. Carriers have been re entering parts of California under the state's Sustainable Insurance Strategy, which requires participating insurers to write policies covering at least 85 percent of properties in those distressed ZIP codes.
If you do end up on the FAIR Plan, the hardening discounts are real money. For policies effective November 15, 2025 or later, the FAIR Plan offers up to twelve wildfire hardening discounts, and a dwelling fire policyholder who earns all twelve may see up to 16.4 percent off the wildfire portion of the premium. Five of them are about the five feet around your house and the yard beyond it. Five are about the structure, including a Class A fire rated roof, enclosed eaves, ember resistant vents, multi pane windows and noncombustible material at the bottom six inches of exterior walls. One more comes from completing all ten, and one from living in a Firewise USA site or a Fire Risk Reduction Community.
Clearing the five feet around your house and the space under your deck costs a weekend. That is the cheapest line item on that list.
Common questions
Does the 29.1 percent increase apply to my policy exactly?
No. It is a statewide average across more than 675,000 FAIR Plan customers. The Department of Insurance approved 29.1 percent after the FAIR Plan asked for 35.8 percent. Homes in higher wildfire risk areas generally see larger increases. Your renewal notice is the only number that applies to you.
Can I be denied a mortgage because of home insurance?
The insurance is not what gets approved or denied. The premium is part of your monthly housing payment, and that payment has to fit your lender's debt to income limits. A premium several hundred dollars a month higher than expected can push a borrower past them. Talk to your loan officer the day you have the quote, not at the end.
Is all of Kern County a wildfire area?
No. The state designates fire hazard severity zones, and Kern County has both. Sixteen Kern ZIP codes appear on the state's distressed area list, and every one of them is in the mountain or foothill parts of the county. None of the eleven City of Bakersfield ZIP codes is on that list. Kern County updated its fire hazard severity zone maps in 2025 after the previous version had stood since around 2007, so the current fire hazard severity zone maps at the Kern County Fire Department are the ones to check for a specific parcel.
How long does a home stay on the FAIR Plan?
There is no fixed term. The FAIR Plan describes itself as a temporary safety net until a traditional carrier will write the property again. So shop the market at every renewal instead of letting it roll, and tell your broker when you have hardened the property. That changes what carriers will consider.
Should I walk away from a house that can only get FAIR Plan coverage?
No, not automatically. Plenty of people own homes in Tehachapi and the Kern River Valley and are glad they do. What you should not do is find out in the last week of escrow. Price the FAIR Plan policy and the DIC policy together, put the combined number in front of your lender, then decide with the real figure in hand.
Does a higher premium lower what a house is worth?
It changes what a buyer can afford to pay, which is not the same thing as value, and I am not going to state a value on any house without looking at what similar homes actually sold for. What the arithmetic above does show is that insurance cost and purchase price compete for the same monthly dollar.
The part most people skip
Insurance used to be the boring line near the end of the escrow checklist. In Kern County it is now one of the three numbers that decide whether a deal works, alongside the rate and the property tax bill. Get the quote early, ask what the DIC policy costs on top of it, and bring both to your lender while you can still walk away.
If you are still weighing renting versus buying when you relocate to Bakersfield, or deciding between the valley floor and the mountain communities, my relocation guide walks through the area and the cost differences: Moving to Bakersfield guide. And if you are already looking at a specific address and want to know what you are walking into, call or text me and I will tell you what I actually see.
Sources: the California FAIR Plan's published policy, premium and exposure data files as of June 30, 2026 and September 30, 2025, available at the California FAIR Plan key statistics page; the California Department of Insurance FAIR Plan page; the Freddie Mac Primary Mortgage Market Survey released September 17, 2026; and local reporting on Frazier Park area nonrenewals published August 14, 2024. Averages and payment figures on this page were computed from those published files.
Rate figures are national survey averages published by Freddie Mac on the dates shown and are not an offer of credit or a rate quote. Payment figures are principal and interest only and are illustrations, not estimates of your cost. Taxes, insurance, mortgage insurance and HOA dues are additional. Only a licensed lender can provide a rate and APR. Insurance premiums shown are averages computed from published FAIR Plan data and are not a quote. Only a licensed insurance broker can quote your property. Equal Housing Opportunity.
Julio Ochoa | Next Level Realty | CalDRE 02198776 | 661-933-8428
Recent Posts