What a Bakersfield Builder Incentive Is Actually Worth
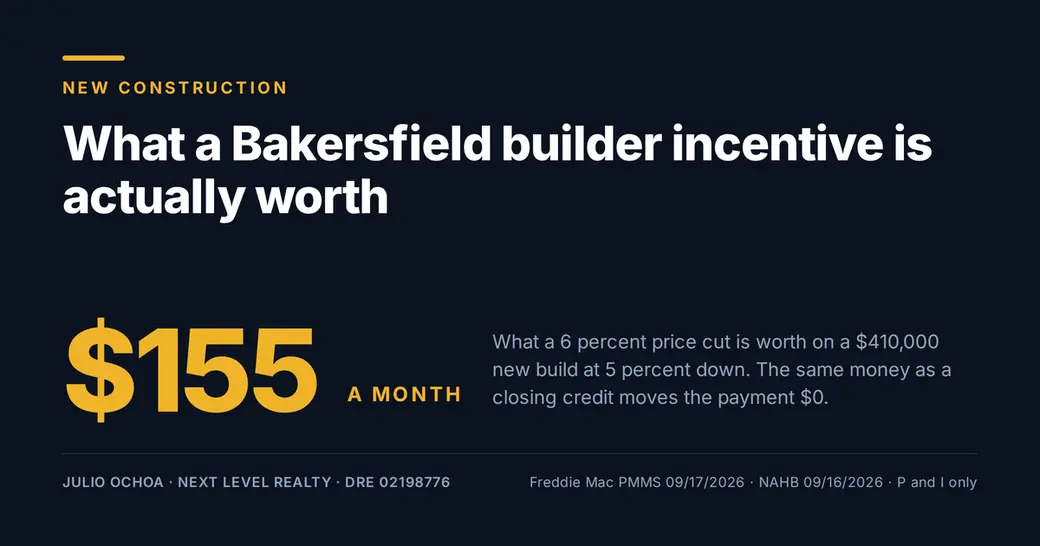
Where the incentive lands decides what it is worth. On a $410,000 new build with 5 percent down, a 6 percent price cut lowers principal and interest by about $155 a month. The same money handed back as a closing cost credit lowers your monthly payment by nothing at all.
Builders in Bakersfield are offering more right now than they were a year ago. Knowing which version of an incentive is worth the most to you is the difference between a good deal and a good-looking deal.
Why builders are handing out more incentives right now
The National Association of Home Builders publishes a monthly builder survey. In the release dated September 16, 2026, 66 percent of builders reported using sales incentives, up from 63 percent in August and the highest share since December. Thirty-eight percent cut prices outright, up from 35 percent the month before. The average price cut held at 6 percent for the sixth month running, and overall builder confidence fell to 32.
That is a national survey, not a Bakersfield count. What it tells you locally is still useful: the builder across the table from you at a Bakersfield sales office very likely has something to give. Your job is to know which form of it puts the most money back in your pocket.
Rates are part of why. Freddie Mac's weekly survey put the 30 year fixed average at 6.95 percent on September 17, 2026, up from 6.76 percent the week before and 6.26 percent a year earlier. When financing costs climb, builders move on price and terms instead of sitting on finished inventory. I broke down what that rate move does to a payment in this post on Bakersfield payments and rates.
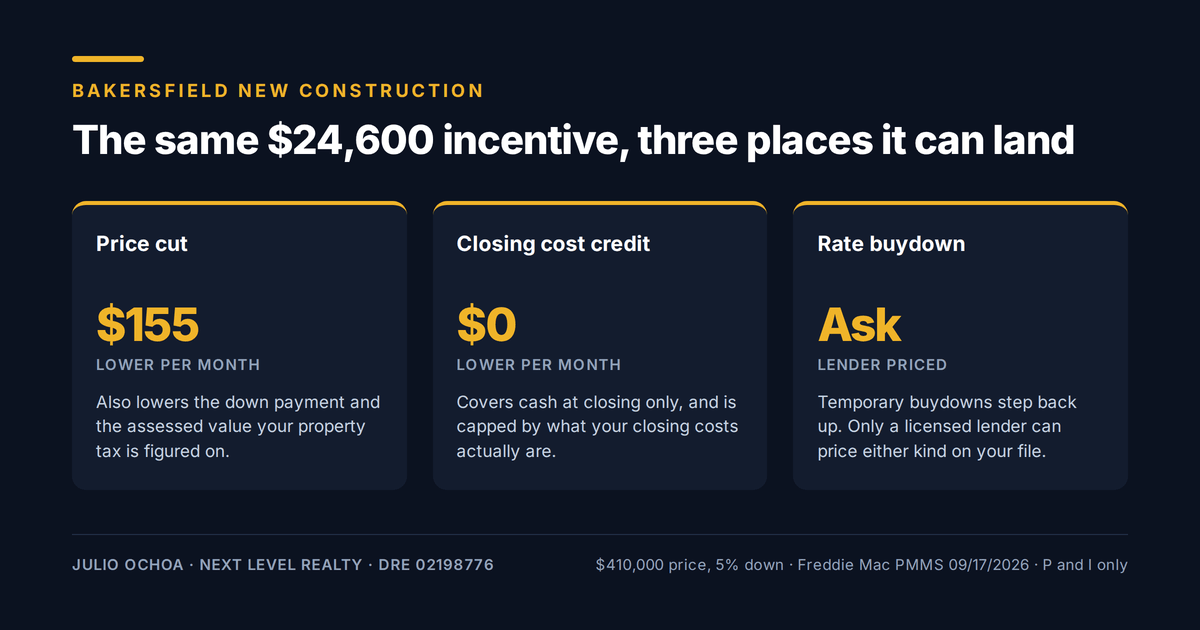
The three incentives you will actually be offered
Builder incentives come in three shapes. They are not interchangeable, and the flyer will not tell you which one is better for you.
| Incentive | What it changes | What it does not change |
|---|---|---|
| Price cut | Loan amount, monthly payment, down payment, and the assessed value your property tax is figured on | Nothing. It is the only one that touches all four |
| Closing cost credit | Cash you bring to the closing table | Your monthly payment, your loan amount, your tax base |
| Rate buydown | Your interest rate, either for the first year or two or for the life of the loan | Your purchase price, your tax base, or what you owe |
Design upgrades and appliance packages are a fourth category, and they are the weakest of the four in cash terms. A $15,000 upgrade allowance is worth $15,000 at builder retail pricing, which is not the same as $15,000 in your pocket.
What a 6 percent price cut is worth on a $410,000 Bakersfield new build
The median listing price across the Bakersfield metro was $410,000 in August 2026, according to Realtor.com data published through the Federal Reserve Bank of St. Louis. Run the math on that number using the September 17, 2026 survey average of 6.95 percent as the illustration rate.
| Full price | 6 percent price cut | |
|---|---|---|
| Purchase price | $410,000 | $385,400 |
| Down payment at 5 percent | $20,500 | $19,270 |
| Loan amount | $389,500 | $366,130 |
| Principal and interest | $2,578 | $2,424 |
So a 6 percent price cut, $24,600, buys you roughly $155 a month, $1,856 a year, and about $55,700 in principal and interest over a full 30 year term. It also drops your cash to close by $1,230 at 5 percent down. If you are still working out what you need up front, my post on how much down payment you actually need in Bakersfield covers the range.
A closing cost credit of the same $24,600 does something different. It covers cash you would have brought to closing, it is capped by what your actual closing costs are, and anything above that cap can go unused. Your payment does not move a dollar.
The part nobody puts in the flyer: your property tax base
California sets your assessed value at what you paid, and Proposition 13 limits how fast that assessed value can grow afterward. A price cut is not a one time discount. It permanently lowers the number your property tax bill is calculated from, for as long as you own the house.
Most Kern County bills land somewhere between 1.1 and 1.25 percent of assessed value once the local add-ons are included. On a $24,600 lower purchase price, that is roughly $270 to $310 a year off the tax bill, every year you own it. A closing cost credit does not touch it. A rate buydown does not touch it. I wrote up the full breakdown in what you will actually pay in Kern County property taxes.
Buying new construction means a supplemental tax bill is coming
This one catches Bakersfield new construction buyers every year. The Kern County Assessor-Recorder reassesses a property on a change in ownership or on completed new construction, and the new value takes effect the first day of the month following that event rather than waiting for the next annual bill. The difference arrives as a supplemental tax bill, issued separately from and in addition to the annual bill mailed in October.
Your first year in a new build is not the year to be surprised by a tax envelope. Ask the builder and your escrow officer how the supplemental bill on your specific lot will work, and set the money aside before you need it.
The catch: the incentive is usually tied to the builder's lender
Most builder incentives are conditional. You get the money if you finance through the builder's affiliated lender, and often if you use their title company too. That is legal and it is normal. It is also why you cannot compare a builder's offer to an outside lender's offer by looking at the rate alone.
What to do about it: get a written loan estimate from the builder's lender and from at least one outside lender on the same day, for the same loan amount and the same purchase price, and compare the total cost rather than the rate. If the builder's incentive outweighs the outside lender's better pricing, take the incentive. If it does not, you now know that in writing instead of guessing. Walk in already pre-approved so you have a real number to measure against, which is the difference I explain in pre-approval versus pre-qualification.
When a rate buydown is the better choice
Two situations. First, if the payment is the thing keeping you from qualifying, a buydown that lowers the payment can be what gets the file approved, where a price cut of the same size may not move enough. Second, builders sometimes spend more on a buydown than they will on a price cut, because a price cut resets the comparable sale for every unsold house behind yours. When the buydown dollars are larger, the buydown can win outright.
The tradeoff to understand: a temporary buydown, often written as a 2-1, lowers your rate for the first year or two and then steps up to the full note rate. You still have to qualify at the full rate, and you need to be honest with yourself about what year three looks like. A permanent buydown does not step up, but it costs the builder more, so the dollars offered are usually smaller. Only a licensed lender can price either one against your actual file.
How to compare two builder offers in ten minutes
- Write down the total dollar value of each incentive. Not the headline, the dollars.
- Ask which ones are conditional on using the builder's lender or title company, and get the answer in writing.
- Ask what the same house sold for on the last three closed lots in that community.
- Put the price cut version and the buydown version in front of a lender on the same day and ask for a loan estimate on each.
- Compare monthly payment, cash to close, and total cost over the years you actually plan to own the house.
- Add the property tax difference, because only the price cut lowers your assessed value.
Common questions
Can I negotiate the price on a new construction home in Bakersfield?
Often you negotiate terms rather than the sticker price. Builders protect the published price because it sets the comparable sale for every remaining lot in the community. That is exactly why incentives exist, and why the money is usually easier to get as a credit or a buydown than as a price reduction.
Is a builder incentive taxable income?
A seller credit or price reduction on a home purchase is generally treated as an adjustment to your basis rather than income, but your situation is yours. Confirm it with a CPA before you file, not after.
Do I need my own agent if the builder has a sales office?
The person greeting you at the builder's sales office works for the builder. You can absolutely walk in alone. If you want someone whose job is reading the contract and the incentive terms on your side of the table, bring your agent to that first visit, because once you have registered yourself I usually cannot step in for you afterward. Every builder sets its own registration rule and timing window, so ask before you go rather than after.
Does a builder incentive lower my appraised value?
A closing cost credit and a rate buydown generally do not change the contract price the appraiser works from. A price cut does, which is the whole reason builders would rather give you the first two.
How do I know the incentive is real and not just the old price?
Ask what the last three closed sales in that community were, lot by lot. Builder pricing is public record once a sale closes. If today's price with the incentive is what people paid two months ago without one, you have your answer.
Is now a reasonable time to buy new construction in Bakersfield?
That depends on your payment, your job, and how long you plan to stay, not on the calendar. What is true as of September 2026 is that more builders are discounting than at any point since December, and rates are higher than they were a year ago. Those two facts pull in opposite directions, and the only way to know which one matters more to you is to see your own numbers.
Before you sign anything
Get your own numbers first. Sit down with a lender, find out what you actually qualify for, then walk into a sales office knowing what the incentive is worth on your file instead of on the flyer. I will go through a builder's offer with you line by line and tell you the parts that are not in your favor, because that is the part most people never hear.
If you are starting from scratch on new construction in Bakersfield, my new construction guide walks through how builder pricing, incentives and timelines actually work: https://bakersfieldnewconstruction.netlify.app
Call or text me at 661-933-8428 and tell me which community you are looking at.
Rate figures are national survey averages published by Freddie Mac on the dates shown and are not an offer of credit or a rate quote. Payment figures are principal and interest only and are illustrations, not estimates of your cost. Taxes, insurance, mortgage insurance and HOA dues are additional. Only a licensed lender can provide a rate and APR. Equal Housing Opportunity.
Julio Ochoa | Next Level Realty | CalDRE 02198776 | 661-933-8428
Recent Posts